What is the market overview and industry significance of the Generative Protein Design Market?
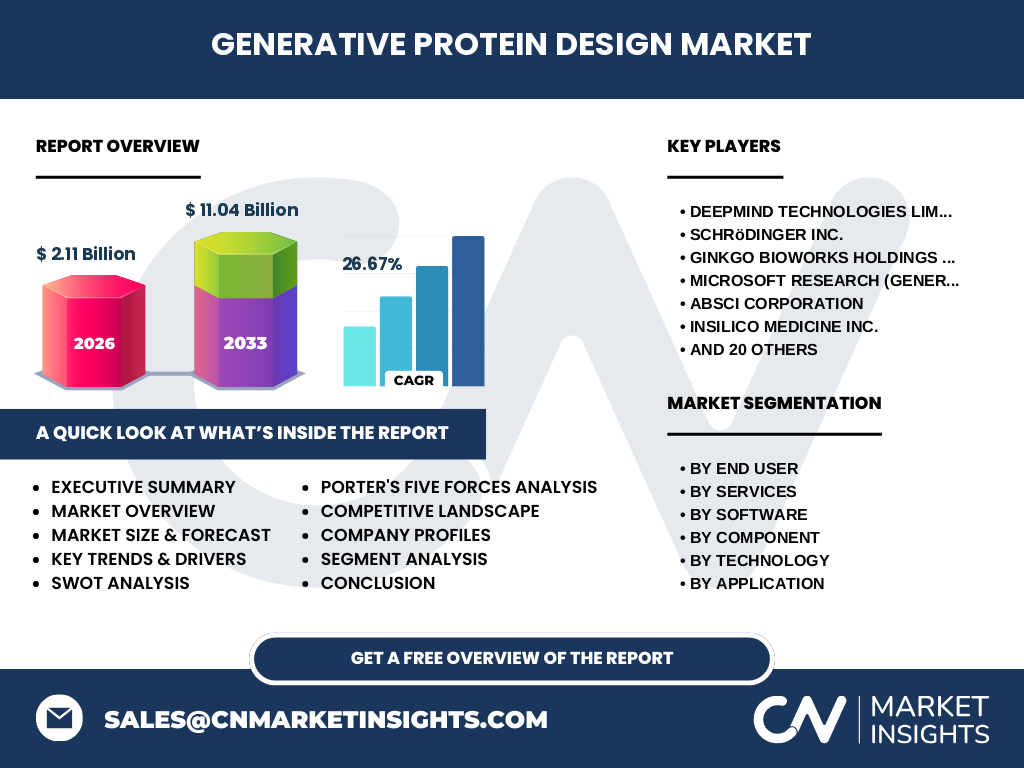
Our analysis indicates that the Generative Protein Design Market is valued at 2.11 Billion in 2026. This sector transforms biomanufacturing by deploying machine learning algorithms to engineer custom proteins, replacing decades of trial-and-error laboratory synthesis with predictive digital modeling. Regulatory bodies like the US FDA and EMA increasingly rely on these computationally validated structures for accelerated drug approvals.
Key market drivers, restraints, challenges, and opportunities shaping Generative Protein Design Market
The market is propelled by plummeting cloud computing costs and advanced deep learning architectures developed by innovators like DeepMind Technologies Limited and Schrödinger Inc. However, severe computational bottlenecks and a scarcity of high-throughput biochemical training data act as primary restraints. Significant opportunities lie in customizing enzymes for toxic waste degradation under stringent environmental mandates.
Emerging trends and growth patterns in Generative Protein Design Market
A defining shift toward multimodal generative models is reshaping the landscape, allowing platforms from pioneers like Generate Biomedicines Inc. to design therapeutic candidates from scratch. This trend favors firms with proprietary wet-lab automation infrastructure capable of rapidly validating computational outputs against physical biological assays.
COVID-19 impact analysis on Generative Protein Design Market and recovery trajectory
The pandemic catalyzed unprecedented venture capital funding into computational biology, permanently validating in silico discovery platforms during global supply chain disruptions for raw chemical reagents. Post-COVID recovery trajectories show sustained institutional investment, as pharmaceutical pipelines demand resilient, computer-generated antibody libraries to outpace viral mutation rates.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is moderately fragmented, featuring agile specialists alongside tech giants. Microsoft Research and Isomorphic Labs Limited leverage massive cloud and algorithmic assets, while specialized entities like Absci Corporation and Insilico Medicine Inc. dominate proprietary end-to-end drug discovery pipelines through strategic pharma partnerships.
Executive summary of key findings for Generative Protein Design Market
Our research confirms the Generative Protein Design Market will expand from 2.11 Billion in 2026 to 11.04 Billion by 2033, achieving a robust 26.67% CAGR. Convergence of cloud services, generative adversarial networks, and synthetic biology creates an urgent imperative for enterprise adoption.
Market forecast and projected growth from 2027 to 2033
Driven by compounding adoption across oncology and industrial biocatalysis, the sector will surge at a 26.67% CAGR between 2027 and 2033, ultimately hitting 11.04 Billion. Investment capital will disproportionately flow toward platforms minimizing clinical trial attrition rates.
Segmentation analysis of the Generative Protein Design Market
The market breaks down across several core verticals: By End User (Pharmaceutical And Biotechnology Companies, Academic And Research Institutes, Contract Research Organizations); By Services (Protein Engineering Services, Computational Biology Services, Consulting Services, Cloud-Based Design Services, Research And Development Services); By Software (Protein Modeling Software, Sequence Design Software, Structure Prediction Software, Simulation And Visualization Software, Data Analysis Software); By Component (Software, Services); By Technology (Deep Learning, Reinforcement Learning, Generative Adversarial Networks, Variational Autoencoders); By Application (Drug Discovery, Enzyme Engineering, Therapeutics, Industrial Biotechnology); and By Protein Type (Enzymes, Antibodies, Peptides, Hormones).
Regional market analysis and geographic distribution
North America dominates global consumption due to high venture capital density and early adoption by major biopharmaceutical hubs near key logistics airports in Boston and San Francisco. Meanwhile, Europe demonstrates accelerated growth supported by stringent European Medicines Agency frameworks favoring sustainable industrial biotechnology solutions.
In-depth regional review of key markets
North American leadership is anchored by robust public-private research grants and widespread integration of cloud-based design services among top-tier contract research organizations. Concurrently, the Asia-Pacific region exhibits the fastest sequential growth, fueled by government-backed biotechnology infrastructure initiatives in Japan, South Korea, and Singapore.
Company profiles and strategic positioning of leading firms
Industry leaders maintain distinct competitive moats: Ginkgo Bioworks Holdings Inc. scales high-throughput cell programming, whereas Cradle Bio B.V. and Profluent Bio Inc. democratize functional protein engineering via intuitive software toolkits. Firms like Arzeda Corporation specialize specifically in computational enzyme design for sustainable chemical manufacturing.
Porter's Five Forces analysis of the Generative Protein Design Market
Bargaining power of buyers is moderate to high, as large pharmaceutical clients demand bespoke, high-affinity therapeutics. Threat of new entrants remains constrained by massive proprietary dataset requirements, yet highly specialized software startups continually disrupt traditional service providers.
SWOT analysis of the Generative Protein Design Market
Key strengths include unprecedented speed in multi-target optimization and precise structural prediction. Weaknesses involve black-box algorithm interpretability concerns raised by regulatory bodies like the FDA. Growth opportunities thrive in industrial biotechnology, while threats center on intellectual property disputes over AI-generated sequences.
Value chain analysis from raw materials to end-users
The value chain flows from foundational cloud infrastructure providers and data curation entities (such as Basecamp Research Ltd.) through algorithmic developers to pharmaceutical enterprises and contract research organizations that manufacture the final therapeutic peptides, enzymes, and antibodies.
Investment insights and strategic high-potential areas
Investors should prioritize integrated platform providers that successfully merge generative AI software with proprietary automated wet-labs. Companies targeting high-margin antibody and enzyme engineering sectors present the most immediate path to venture liquidity and strategic acquisition.
Conclusion and key takeaways for stakeholders
Reaching 11.04 Billion by 2033, the Generative Protein Design Market represents a fundamental paradigm shift for life sciences. Stakeholders must secure proprietary biological data assets and forge strategic partnerships across software and wet-lab operations to capture market share.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing global trade registry data, primary qualitative interviews with C-suite biotechnology executives, and secondary macroeconomic indicators across major patent and financial databases to ensure accurate market sizing.
Scope of the report and coverage parameters
This report encompasses comprehensive global analysis of the Generative Protein Design Market across software, services, technologies, and end-user segments from 2026 through 2033, while explicitly excluding traditional non-computational recombinant protein expression techniques.
Recent developments in the Generative Protein Design Market
Recent milestones feature strategic licensing agreements between computational pioneers like Insilico Medicine Inc. and global pharma giants, alongside product launches of advanced sequence design software by agile innovators such as Latent Labs Inc. and Peptone Limited.